
Senior Loan Officer · Tampa Bay
Tampa Bay home loans, from the lender who picks up the phone.
Joe Andrews has spent 25+ years helping families buy, refinance and invest across Florida, Georgia and eight other states, with every CMG Home Loans program at his fingertips, including the All In One Loan®. More than 300 clients have reviewed the experience, and they rate it 4.97 out of 5.
The record
Client ratings for Joe Andrews
average across 304 reviews
Rated 4.97 out of 5 across 304 reviews on Testimonial Tree, and 5.0 out of 5 across 37 Google reviews.
- Testimonial Tree
- 4.97 ★ · 304
- 5.0 ★ · 37
Joe Andrews is hands down the best we have ever worked with! He recently helped us close on our house in Wesley Chapel, and the entire experience was flawless. He took the time to understand exactly what we needed, navigated the closing process smoothly, and kept us informed every single step of the way.
“Joe Andrews is hands down the best we have ever worked with!”
Haya S.Purchase · Wesley Chapel “He maintained contact and provided us with resources that put us in position to make homeownership possible.”
Keisha C.First home “Joe has worked with us for almost 3 years navigating us to help build our credit…”
Alana K.Credit-building to closing “He was professional, responsive, and always kept us updated.”
Luis G.Purchase “We have used Joe on several occasions and would highly recommend him to anyone!”
Steven S.Repeat client “I had an amazing first time home buying experience”
Jeffery D.First home “His ability to break down complex lending information in a clear, approachable way was incredibly valuable.”
Michelle G.Real estate team “He communicated thoroughly every step of the way…”
Michael C.First home “Once we started the process, he was available all hours of the day to answer our questions.”
Antonia V. “The closing was done extremely fast.”
Jincymol K. “He took his time with us and made us feel right at home.”
Anthony T.
“Joe was always available when I needed guidance and consistently went above and beyond…”
Kate-lynn J.Purchase “Joe’s team worked hard, (even on the weekends), to help make this process move on greased wheels.”
Todd H.Purchase “They kept my Realtor in the loop as requested making the loan process smoother”
Maryann F.Purchase “During the process he answered all our questions in a timely manner.”
Maria R. “Joe worked tirelessly to provide us with the best financing possible.”
Juan G. “Great service and very helpful!”
Kamille W. “What stands out most about Joe is that his support didn’t stop after closing…”
Agj “Professional, precise, and prompt!”
George C. “He kept us informed at every step and made what can be a stressful process feel smooth and manageable.”
Hong D. “Y’all were great the whole group of you.”
Linda H.
About Joe
Tampa Bay since the ’90s.
Atlanta born and raised.
Joe’s reputation rests on one simple habit: he’s the loan officer you can actually reach. As a Senior Loan Officer at CMG Home Loans, he works with first-time buyers, move-up families, veterans, investors, and the real estate agents who serve them. Every one of them gets the same clear explanations and quick answers.
He has called Tampa Bay home since the 1990s and knows its neighborhoods and market cycles from Wesley Chapel to South Tampa. He grew up in Atlanta, so Georgia buyers get a lender who knows both ends of I-75.
Clients keep saying the same things about him: he explains every step, he moves quickly when it counts, and he doesn’t disappear after closing.
- Experience
- 25+ years in mortgage lending
- With CMG Home Loans
- Since 2017
- Specialty
- All In One Loan® specialist
- Licensed in
- FL, GA, AL, MN, MI, IN, CA, AZ, VA & TN
Serving buyers across
- Tampa
- South Tampa
- Westchase
- Brandon
- Riverview
- Wesley Chapel
- Lutz
- Land O’ Lakes
- St. Petersburg
- Clearwater
- Apollo Beach
- Plant City
- Licensed in FL, GA, AL, MN, MI, IN, CA, AZ, VA & TN
Loan programs
The right loan, not just the first one that fits.
Joe has the full CMG Home Loans lineup to work with, including programs you won’t find at most banks. Here’s what’s available.
Only at CMG
- CMG exclusiveAll In One Loan®A 30-year first-lien HELOC with a built-in checking account. Every deposit lowers the balance your interest is calculated on.Learn more
- Down payment crowdfundingHomeFundIt™Family, friends and employers can contribute to your down payment online, and eligible first-time buyers can earn a matching closing-cost grant.Visit CMG (opens in a new tab)
- Down payment assistanceCommunity ONE GrantA 2% grant, up to $6,000, with down payments as low as 1% for buyers who meet income and location requirements.Visit CMG (opens in a new tab)
- For sellers and agentsList & Lock™Lets a listing advertise a locked interest rate that qualified buyers can use, so a home can stand out without a price cut.Learn more
Every core program
- ConventionalFannie Mae and Freddie Mac financing with fixed or adjustable terms, for purchases and refinances.Best for: Solid credit, steady income
- FHAGovernment-insured loans with lower down payment options and more flexible credit guidelines.Best for: First-time and rebuilding buyers
- VAFinancing backed by the Department of Veterans Affairs, often with no down payment required.Best for: Veterans, service members, eligible spouses
- USDARural Development loans for eligible suburban and rural areas, with no down payment for qualified buyers.Best for: Buyers outside the urban core
- JumboFinancing above conforming loan limits for higher-priced homes across Tampa Bay and beyond.Best for: Waterfront and luxury purchases
- FHA 203(k) RenovationRoll the cost of repairs or upgrades into one loan with the purchase or refinance.Best for: Fixer-uppers and older homes
- HomeReady®Fannie Mae’s low-down-payment program for income-eligible buyers, with flexible funding sources.Best for: Moderate-income buyers
- Home Possible®Freddie Mac’s low-down-payment option for income-eligible buyers.Best for: Moderate-income buyers
Payment estimator
All In One Loan® not for you? Try one of our most popular traditional loans.
An educational tool for ballparking a monthly payment on a 30-year fixed, 15-year fixed, FHA or VA loan. Its estimates use the latest weekly national average rates from Freddie Mac as a starting point. Everything it shows is an estimate, not a quote.
Educational estimate, not a quote
Example starts at the national average for the week of Oct 1, 2026: 7.28%
Latest rates used in these estimates
National averages from Freddie Mac’s Primary Mortgage Market Survey® (opens in a new tab), week of Oct 1, 2026. Freddie Mac publishes new averages every Thursday, and this estimator picks them up automatically.
- 30-year fixed averageStarting rate for 30-year fixed, FHA and VA
- 7.28%
- 15-year fixed averageStarting rate for 15-year fixed
- 6.60%
Estimated monthly payment (example)
$3,452/mo
- Principal & interest
- $2,617
- Property taxes
- $390
- Homeowners insurance
- $333
- Mortgage insurance
- $112
- Est. loan amount
- $382,500
- Est. interest over 30 years
- $559,660
Same home, side by side (estimates)
| Program | Example rate | Est. monthly | Est. interest |
|---|---|---|---|
| 30-year fixed | 7.28% | $3,452 | $559,660 |
| 15-year fixed | 6.60% | $4,188 | $221,049 |
| FHA 30-year | 7.28% | $3,545 | $569,454 |
| VA 30-year | 7.28% | $3,373 | $566,656 |
For educational purposes only. This is a hypothetical estimate based on the numbers above, not a quote, rate lock, loan offer or commitment to lend. Example rates start at Freddie Mac Primary Mortgage Market Survey® national averages for the week of Oct 1, 2026; they are not rates offered by CMG Home Loans. Freddie Mac doesn’t publish FHA or VA averages, so those rates start at the 30-year conventional average. Your actual rate, APR and payment depend on credit, loan amount, down payment, property type, occupancy and market conditions. Conventional mortgage insurance is a rough estimate for strong credit. FHA figures include the 1.75% upfront mortgage insurance premium financed into the loan and the annual premium. VA figures include a first-use funding fee financed into the loan; some veterans are exempt and subsequent use costs more. Taxes and insurance are estimates. Loan limits and program guidelines apply.
The All In One Loan®
Your paycheck, working against your mortgage every single day.
CMG’s All In One Loan® combines your mortgage and your checking account. Deposits cut the balance the moment they land, and interest is charged only on what you actually owe each day.
- DepositYour paycheck goes straight into the loan’s built-in checking account.
- SweepEvery dollar immediately reduces the balance that interest is calculated on.
- SpendYour money stays available 24/7 by debit card, checks and bill pay.
One month on a $400,000 All In One Loan®
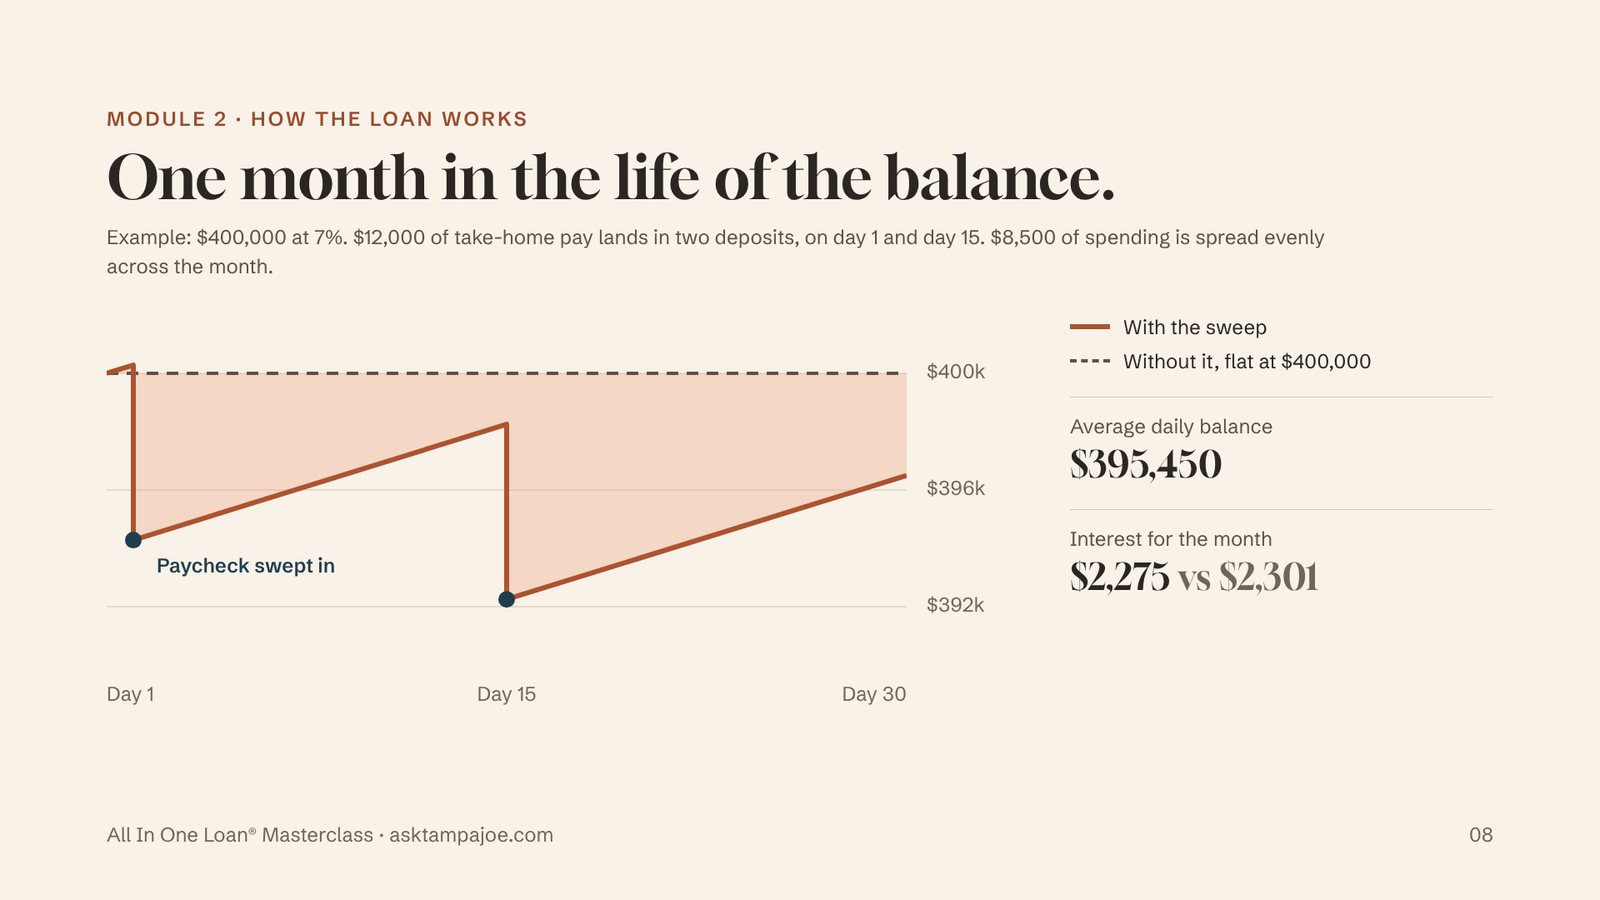
In this example the sweep lowers the average balance to $395,486, so interest for the month is $2,275.40 instead of $2,301.37, a savings of $25.97.
That’s about $312 a year from the sweep alone. The bigger win is what it makes automatic: every spare dollar keeps pulling the balance down, month after month, while staying available to spend.
See what that does over the life of the loanHypothetical example: $400,000 balance, 7% rate for both lines, $12,000 monthly take-home pay in two deposits, $8,500 of monthly spending. Not a quote or offer; actual rates and results vary. Rate could rise during the life of the loan. The All In One Loan® does not use a traditional amortization schedule. Principal is paid through deposits into the All In One Loan® sweep-checking account. Interest is computed based on the nightly unpaid principal balance. Each day’s interest is totaled once each month ends.
Free course
Want the whole story? Take the free All In One Loan® masterclass.
Six short modules from Joe on how the loan works, what the math really says, and who it fits. Every number is computed and every source is named, so you can decide for yourself.
- How mortgages cost money
- How the loan works
- The fine print
- The honest math
- Fit, risk and myths
- Getting started
 6 modules · 32 slides · free
Working with Joe
From first call to closing, and beyond.
There are no hand-offs to a call center. You work with Joe and a small team who know your file.
- Step 1
A real conversation
Your goals, your numbers and your timeline, before any paperwork.
- Step 2
Pre-approval that holds
Income, assets and credit reviewed up front, so there are no surprises at closing.
- Step 3
Shop, lock, and stay informed
You, and your agent if you’d like, get updates at every milestone.
- Step 4
Close on time
A team built around deadlines, even when that means weekends.
- Step 5
Still your lender after closing
Market updates, refinance checkups, and a number that still gets answered.
For real estate agents
A lending partner who makes you look good.
Pre-approvals that hold up, updates you don’t have to chase, and CMG programs that help your buyers and sellers win.
Call Joe about a client- Pre-approvals that hold. Documented up front so your deal doesn’t unravel in underwriting.
- You stay in the loop. Status updates to you and your client at every milestone.
- List & Lock™. Help a listing stand out with a locked rate qualified buyers can use.
- Down payment help. HomeFundIt™ and the Community ONE Grant for buyers who are close.
- Investor-friendly. The All In One Loan® can finance second homes and rentals.
“They kept my Realtor in the loop as requested making the loan process smoother”
Questions, answered
CMG programs & the All In One Loan®, explained.
Straight answers to what people ask Joe most. Don’t see yours? Just call.
What is CMG’s All In One Loan®?
The All In One Loan® is a 30-year, first-lien home equity line of credit (HELOC) with a 30-year draw period and a built-in checking account. It takes the place of a traditional mortgage, and it can be used to buy a home or to refinance one.
Your paychecks and other deposits go straight into the account, where they automatically reduce the loan balance. The money stays available for bills and spending through a debit card, checks, bill pay and mobile banking. CMG has offered it since 2005.
How does the All In One Loan® save interest without a lower rate?
Interest is calculated every night on your actual balance, then totaled at the end of the month. Every dollar you deposit lowers that balance until you spend it, so money that would normally sit in a checking account is working against your loan the whole time it’s there.
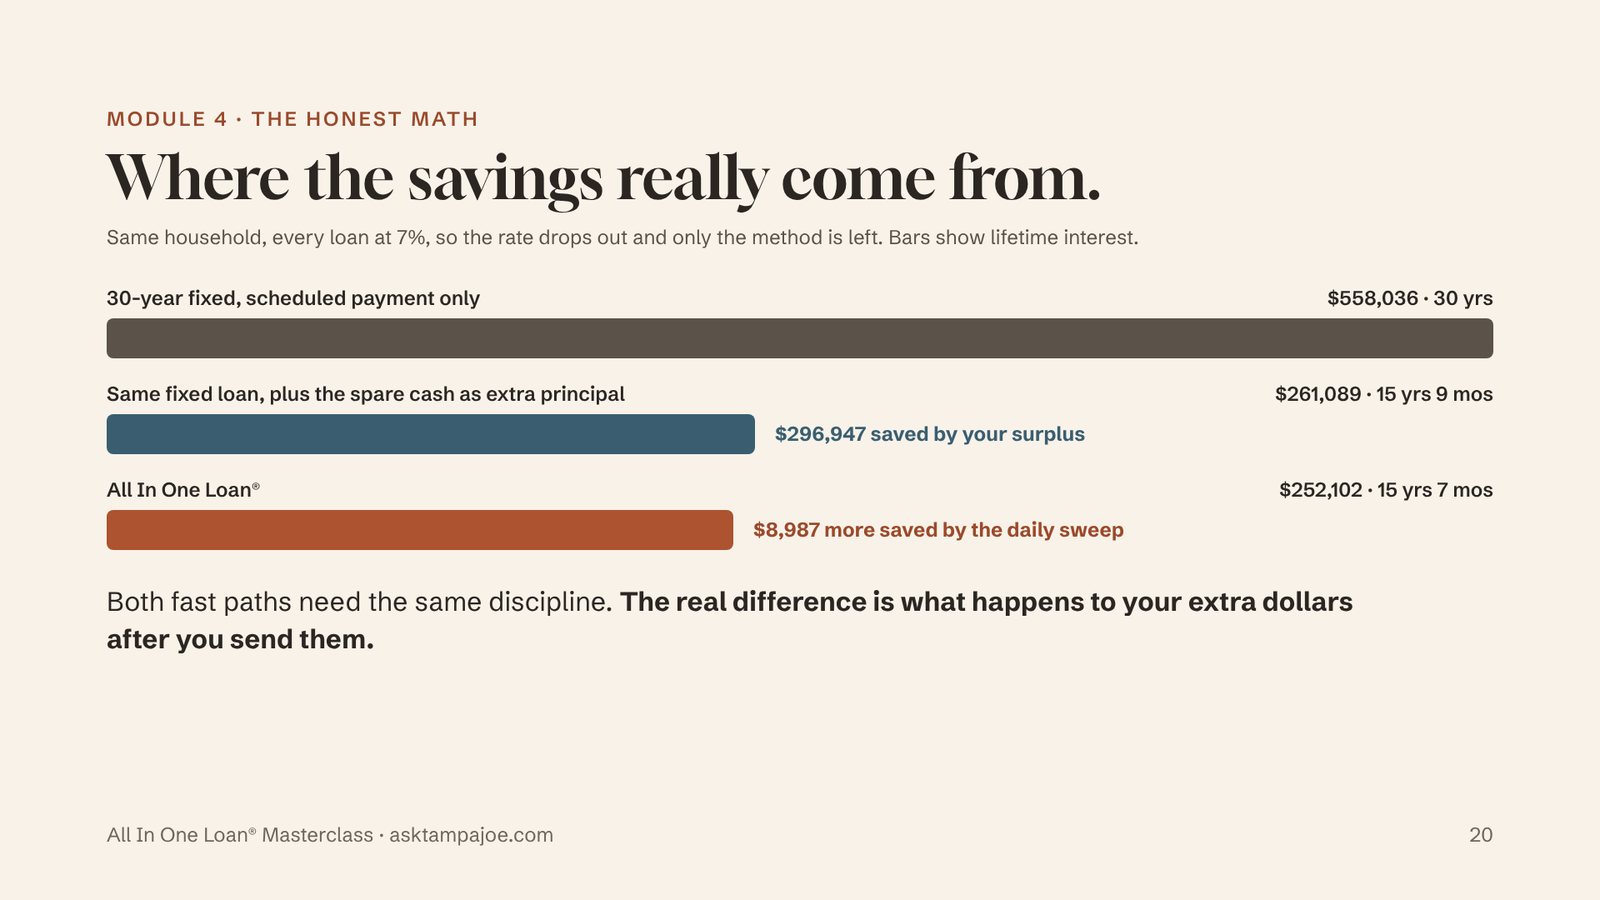
The rate is only one part of what a loan costs. The other two are how much you owe and how long you owe it. If you regularly bring in more than you spend, the surplus keeps pulling the balance down, and you can pay the home off years sooner than with a standard 30-year schedule.
Is the All In One Loan® right for everyone?
No. It’s built for people who are cash-flow positive, meaning they regularly bring in more than they spend, and who are disciplined with a line of credit. If you routinely spend more than you earn or use credit to cover monthly expenses, a traditional fixed-rate mortgage is usually the better fit.
Joe can run your real numbers through CMG’s All In One Loan® comparison simulator so you can see how it stacks up against a traditional mortgage before you decide.
Can I use the All In One Loan® to buy a home, a second home or an investment property?
Yes. Per CMG’s program materials:
- Purchases and refinances are both eligible.
- It can finance single-family homes, condos and 2–4 unit properties as a primary residence, second home or investment property.
- Refinances can be rate-and-term or cash-out.
- Minimum down payment depends on occupancy: 10% for a primary residence, 20% for a second home and 30% for an investment property.
- Loan amounts go up to $3 million on primary residences and second homes, and $1 million on investment properties. Availability can be limited by location.
Many owners use the line’s available equity to buy additional properties.
Is the All In One Loan® rate fixed?
No. The rate adjusts monthly. It’s a published index, the One-Year Constant Maturity Treasury, plus a margin that’s set at closing and never changes. Margins range from 2.50% to 4.00% depending on your credit and equity.
Every loan has a 3.75% floor and a lifetime cap of 6% above the starting rate. There is no balloon payment and no prepayment penalty.
Which loan programs does Joe Andrews offer?
Joe offers the full CMG Home Loans lineup for purchases and refinances, plus CMG’s own programs:
- Conventional, FHA, VA, USDA and jumbo loans
- FHA 203(k) renovation loans
- HomeReady® and Home Possible® low-down-payment programs
- CMG’s All In One Loan®, HomeFundIt™ and the Community ONE Grant
CMG Home Loans holds approvals with HUD, VA, RHS, Ginnie Mae, Fannie Mae and Freddie Mac.
What is HomeFundIt™?
HomeFundIt™ is CMG’s online down payment gifting platform. You create a profile, share your homebuying story, and family, friends, coworkers or your employer can contribute to your down payment.
Through its Closing Costs Covered grant, CMG adds $2 for every $1 raised through online gifts, up to 1% of the purchase price or $2,000*, whichever is less. The grant is for first-time buyers who complete homebuyer education before signing a purchase contract.
*Grant is a $2-to-$1 match on regular down payment gifts received on HomeFundIt™, up to the lesser of $2,000 or 1% of purchase price for first time buyers, as defined by Fannie Mae, who complete homebuyer education prior to signing a purchase contract. Talk to your loan officer or visit your HomeFundIt™ dashboard for next steps. Find a housing counselor near you by visiting https://www.hud.gov/counseling.
Grant funds are applied to nonrecurring closing costs. If closing costs are fully paid by seller or interested party, grant funds can be used to buy down the rate. Grant funds cannot be used towards a down payment. Visit https://www.homefundit.com/Grant for complete terms and conditions.
What is the Community ONE Grant?
It’s a CMG down payment assistance program that offers a 2% grant, up to $6,000, with down payments as low as 1%. It’s available to buyers who meet income requirements and are purchasing in eligible areas. Joe can check your eligibility against a specific address.
What is List & Lock™?
List & Lock™ is a CMG program for home sellers and their agents. It lets a listing advertise a locked-in interest rate that qualified buyers can use when they finance through CMG. That can help a home stand out without a price cut. Terms and availability vary, so talk with Joe before you list.
Where is Joe licensed to lend?
Joe is based in Tampa and is licensed to lend in Florida, Georgia, Alabama, Minnesota, Michigan, Indiana, California, Arizona, Virginia and Tennessee. He works with buyers and homeowners throughout Tampa Bay, and he grew up in Atlanta. You can check his current state licenses anytime on NMLS Consumer Access under NMLS #320789.
How do I get started?
Call or text Joe at 813.781.9769, email jandrews@cmgfi.com, or start a secure application online. A first conversation costs nothing and doesn’t commit you to anything. It’s simply a chance to look at your goals, your numbers and the options that make sense.
Let’s talk
Your move starts with one call.
Whether you’re buying your first home, refinancing, or trying to figure out if the All In One Loan® fits, a first conversation with Joe costs nothing and commits you to nothing.